Sovereign Finance Solutions
Transforming National Aspirations into Economic Reality
In an era where fiscal prudence meets ambitious national development objectives, IFB designs sovereign financing solutions for exactly this tension. We recognise that modern governments require more than conventional lending: they demand innovative financial engineering that preserves fiscal sovereignty whilst opening transformative capital.
Our Complete Suite of Sovereign Financing Instruments
Revenue Securitisation Programmes
We assess whether identifiable public revenue streams can support a financing for a defined development purpose. The assessment covers the legal authority to assign or pledge revenues, their historical performance, collection controls, competing claims and sensitivity to economic shocks. Pledging future receipts brings capital forward but also commits future fiscal resources. The resulting debt, guarantees and contingent exposures must be assessed and reported under the applicable public-finance framework. Pricing and available proceeds depend on those findings and investor demand.
Natural Resource Monetisation Facilities
Future royalties or export receipts may support financing where production, ownership, collection rights and available volumes can be independently established. Any proposal must be tested against commodity-price volatility, operating and delivery risks, existing claims on the revenues and the State’s continuing fiscal needs. Financing against future resource income creates repayment obligations; it does not, by itself, reduce public indebtedness or preserve reserves. IFB evaluates the full economic and fiscal cost before recommending a structure.
Infrastructure Development Through Public-Private Partnership
IFB assesses whether a public-private partnership provides better value than conventional public procurement and funding. Project revenues may contribute to repayment, but governments can remain exposed through availability payments, guarantees, minimum-revenue commitments, termination payments or support to a public offtaker. Those direct and contingent commitments must be quantified, approved, budgeted and monitored. Project-specific financing can allocate risks more effectively; it cannot automatically insulate the general budget.
Special Purpose Vehicle Architecture
A special-purpose vehicle can establish clear ownership, segregate project cash flows and define contractual rights among the State, investors and operators. Its creation does not determine whether the associated borrowing or commitments belong in public accounts or affect sovereign credit assessments. That treatment depends on the substance of the State’s control, guarantees, payment obligations and risk exposure, assessed under applicable law and accounting standards. IFB uses SPVs where they improve governance and enforceability, with the related fiscal commitments expressly identified.
Innovative Bond Structuring and Placement
We pioneer sophisticated bond structures that segment sovereign risk by revenue source, creating targeted investment opportunities that attract diverse international capital. Our tranched approach, allocating specific revenue streams to distinct investor classes, optimises pricing whilst broadening the sovereign’s investor base.
Reserve-Enhanced Credit Facilities
For nations with substantial foreign exchange reserves or access to multilateral guarantees, we structure enhanced credit facilities that leverage these strengths to secure preferential terms. Any reserve commitment, collateral arrangement or third-party guarantee is assessed for its cost, effect on available liquidity, legal enforceability and treatment in the sovereign’s fiscal and reserve reporting. Preferential terms are an objective for market testing, not an assured result.
The IFB Advantage
Exceptional Expertise
Our sovereign finance team comprises former treasury officials, central bankers, and capital markets veterans who understand the unique constraints and opportunities facing modern governments.
Global Reach, Local Understanding
With presence across major financial centres and emerging markets, we combine international best practice with precise appreciation of local contexts.
Risk Mitigation Excellence
Every structure we create incorporates multiple layers of risk mitigation, from syndication strategies to guarantee mechanisms, ensuring resilient outcomes across economic cycles.
Transparent Partnership
We believe sovereign finance should enhance, not obscure, fiscal transparency. Our structures are designed to meet the highest international standards of disclosure and governance.
Transforming Vision into Reality
The path from national ambition to economic achievement requires more than capital: it demands a partner who understands the delicate balance between fiscal responsibility and development imperatives. IFB offers precisely this partnership.
We invite sovereign entities to engage with us in a full diagnostic process, wherein we:
- Analyse your unique revenue architectures and asset bases
- Identify optimal financing structures aligned with your risk parameters
- Design bespoke solutions that preserve fiscal flexibility whilst delivering transformative capital
- Execute transactions with precision, transparency, and unwavering commitment to your sovereign interests
Initiate Your Transformation
The convergence of global capital markets expertise and sovereign financing innovation positions IFB as your ideal partner in national development. We stand ready to deploy our full capabilities in service of your economic objectives.
Contact our Sovereign Finance Division to commence a confidential consultation. Together, we shall architect financial solutions that honour your fiscal sovereignty whilst unleashing your nation’s economic potential.
IFB: Where Sovereign Ambition Meets Financial Innovation
For confidential discussions regarding your sovereign financing requirements, please contact our Global Head of Sovereign Finance directly. All enquiries are handled with the utmost discretion and diplomatic protocol.
Sovereign & Quasi-Sovereign Project-Finance Compendium
Executive Prelude – Diagnosing the Funding Gap
Many publicly announced infrastructure initiatives in emerging markets never reach financial close. The recurrent pathology is structural mis-alignment: ministries often transpose domestic procurement rules, or donor templates from a bygone era, onto capital-market transactions whose risk allocation, tenor, security package and pricing no longer match investors’ expectations. The inevitable result is a stagnant tender, repriced spreads, or outright cancellation.
IFB’s Sovereign & Quasi-Sovereign (SQS) desk exists to rectify this mis-match. We begin by reconstructing the capital stack so that, before the first spade of earth is turned, each risk is corralled to the balance-sheet best equipped to bear it, fees are transparently front-loaded to protect fiscal space, and covenants reflect real-time market clearing levels.
I. Financing Modalities at a Glance
Sovereign financing modalities
| # | Modality | Indicative tenor | Typical use | Up-front professional and arranger fees |
|---|---|---|---|---|
| 1 | Bilateral sovereign loan | 3–15 years | Budget support; small capex imports | Retainer, technical due diligence fee, structuring fee |
| 2 | Syndicated sovereign loan | 5–12 years | Fiscal or counter-cyclical facility of USD 300 million or more | Underwriting fee, syndication fee, break-up fee |
| 3 | Treasury bond underwriting | 5–30 years | Hard-currency benchmark or local bond market-making | Underwriting spread, roadshow coordination fee |
| 4 | Limited-recourse project finance | 8–25 years | Power, transport, digital backbone | Model audit fee, ESG verification fee, structuring fee |
| 5 | Public-private partnership debt (BOT, DBFO) | 10–35 years | Toll road, airport, hospital, water desalination | Retainer, concession bid advisory fee, debt arrangement fee |
| 6 | Export credit (buyer’s credit) | 5–15 years | EPC contract with foreign content of 30% or more | ECA premium handling spread, legal documentation fee |
| 7 | Supplier’s credit and receivables discounting | 1–5 years | Rolling stock, ICT hardware, defence materiel | Discount margin on receivables, structuring fee |
| 8 | Revolving and standby credit line | 1–4 years | FX buffer, disaster-response liquidity | Commitment fee, agency fee |
| 9 | Bridge financing | Up to 24 months | Bridge to a Eurobond or multilateral drawdown | Underwriting fee, swap execution margin |
| 10 | Contingent credit facility (catastrophe DDO, pandemic DDO) | 15–20 years (3–5 year drawing window) | Climate, commodity-price or health shocks | Arrangement fee, availability fee pre-funded |
| 11 | Islamic finance (sukuk, istisnaʿ, ijara) | 5–20 years | Domestic investor base, Shariah jurisdictions | Shariah structuring fee, certificate issuance fee |
| 12 | Green, social or sustainability-linked bond or loan | 5–30 years | Climate mitigation, social housing, SDG-aligned | Impact verification fee, KPI calibration fee |
| 13 | Commodity-backed “resource for infrastructure” loan | 5–15 years | Oil-backed refineries, mineral rail spurs | Off-take valuation fee, hedge execution margin |
| 14 | Debt-for-nature or debt-for-development swap | Bespoke | Conservation trust financing, policy reform | Swap structuring fee, monitoring trustee fee |
| 15 | Equity or quasi-equity in a state-owned enterprise | Open | Telecoms, utilities, ports | Placement fee, dividend monitoring fee |
BOT: build-operate-transfer; DBFO: design-build-finance-operate; EPC: engineering, procurement and construction; ECA: export credit agency; DDO: deferred drawdown option; KPI: key performance indicator.
II. Narrative Deep-Dive into Each Instrument
1. Bilateral Sovereign Loan
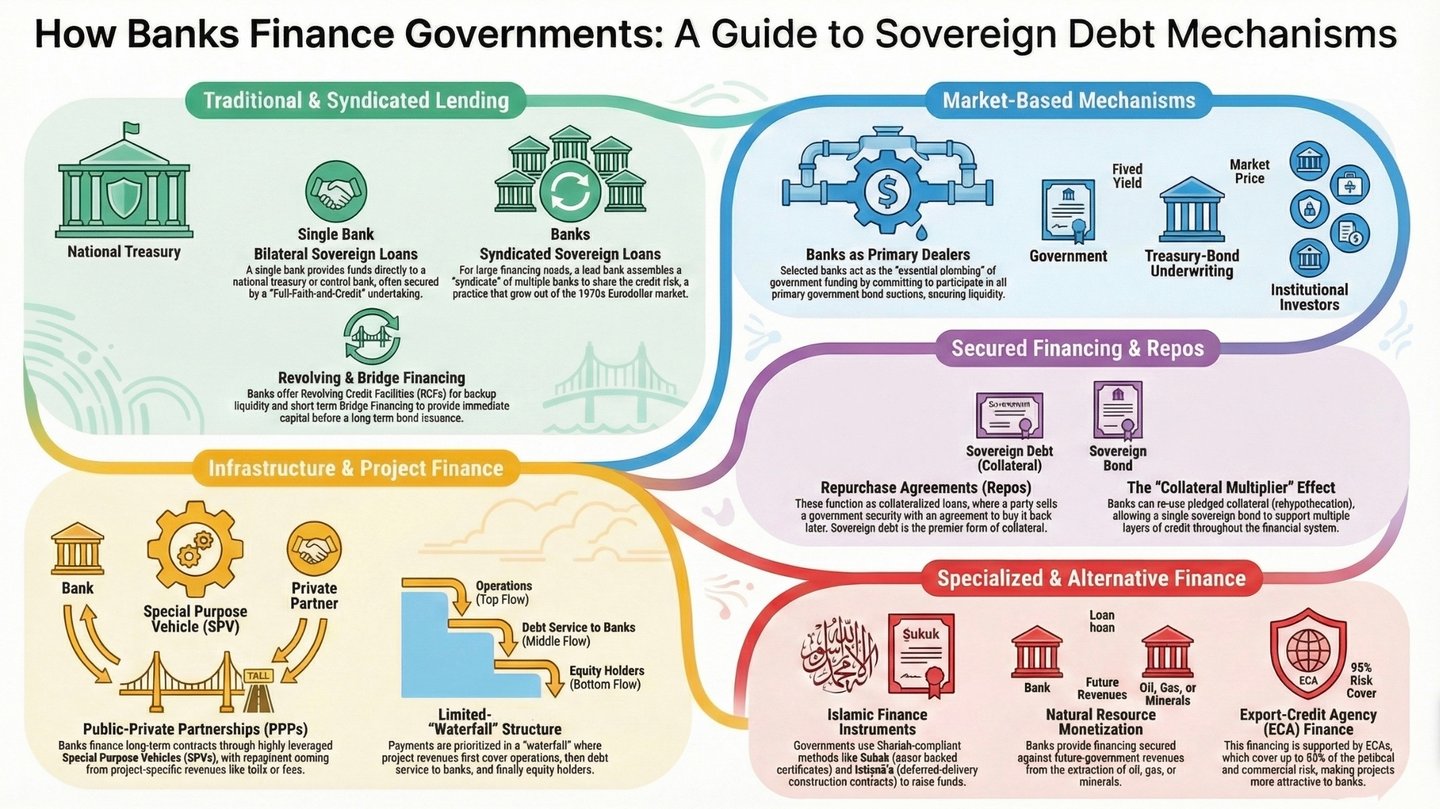
- Essence. IFB funds the Treasury or central bank directly. Documentation is short-form; proceeds can be deployed flexibly.
- Security. Full-Faith-and-Credit (FF&C) undertaking plus negative-pledge and pari-passu clauses.
- Pricing Reference. Priced off the sovereign’s Eurobond curve, adjusted for tenor and liquidity.
- Up-Front Fees.
- Retainer (USD 0.5-1.0 m) at mandate.
- Technical-Due-Diligence Coordination Fee (5-8 % uplift on Big-Four audit invoices).
- Structuring Fee (50-100 bp of loan), booked on credit approval.
2. Syndicated Sovereign Loan
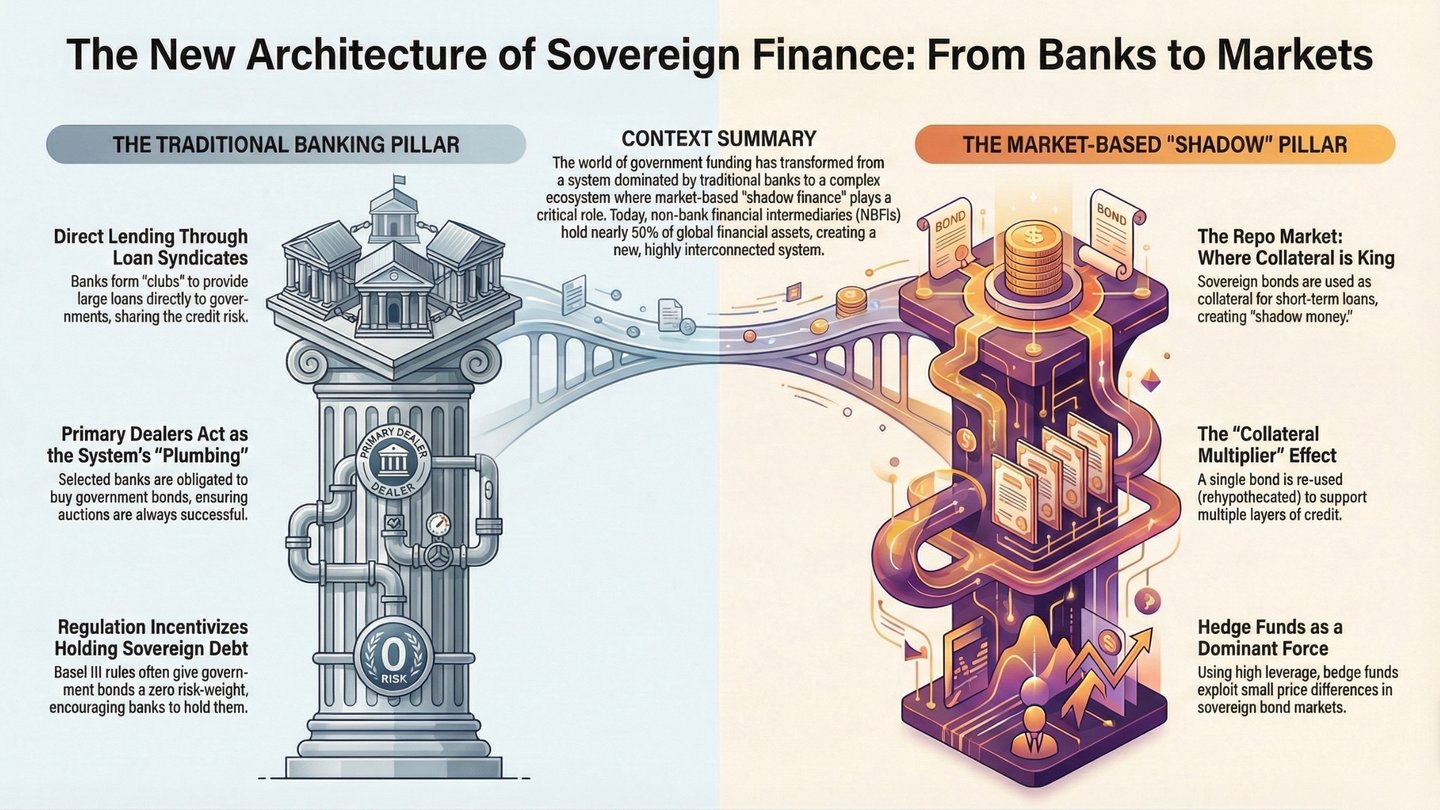
- Why Syndicate? Ticket sizes > USD 300 m and Basel concentration limits dictate a club.
- IFB’s Role. Mandated Lead Arranger (MLA) underwrites 100 %, allocates participations, and remains Facility Agent.
- Fee Stack.
- Engagement Retainer (non-refundable).
- Underwriting Fee (75-200 bp “gross” spread between underwritten and distributed price).
- Syndication / Participation Fee (25-75 bp carve-out retained by MLA).
- Break-Up (Abort) Fee (USD 2-5 m) payable if borrower migrates to an alternate arranger.
3. Treasury-Bond Underwriting
- Structure. Hard-currency Regulation-S/144A global note or local-currency benchmark.
- Risk Transfer. IFB commits to a fixed “take-down” yield, selling to asset-managers at market clearing price.
- Economics. Underwriting Spread 40-200 bp, plus Road-show Coordination Fee (~USD 300 k).
4. Limited-Recourse Project Finance
- Cash-Flow Priority. Waterfall: operating costs and taxes → senior debt service → Debt-Service Reserve Account (DSRA) top-up → maintenance reserve → distributions to equity, subject to a lock-up test.
- Typical Enhancements. Multilateral Partial-Risk Guarantee (PRG), Political-Risk Insurance (PRI), escrow, step-in rights.
- Modelling Mandate. IFB demands an independent Model-Audit (USD 0.15-0.35 m) and levies a Financial-Model Review Fee (USD 0.2 m).
5. Public-Private Partnership (PPP) Debt
- Concession Variants. BOT (Build-Operate-Transfer), DBFO (Design-Build-Finance-Operate).
- Termination Payments. Government undertakes to repay senior debt at predetermined equity IRR upon political force-majeure.
- Advisory Fees. Concession-Bid Advisory (USD 1-3 m) and Debt-Arrangement Fee (75-125 bp).
6. Export-Credit / Buyer’s Credit
- Cover. Up to 95 % of political and commercial risk by an ECA such as Germany’s federal Hermes cover or SACE (Italy).
- OECD Premium. Set under the OECD Arrangement by country risk category and tenor; usually financed into the loan.
- IFB Spread. Retains 3-5 % Handling Spread on the financed premium.
7. Supplier’s Credit & Receivables Discounting
- Mechanics. EPC contractor accepts promissory notes; IFB purchases at a discount (risk-free reference rate such as SOFR or €STR, plus margin).
- Up-Front Income. Discount Margin (3-5 % of face value) recognised immediately.
8. Revolving & Stand-by Credit Line
- Draw Discipline. Availability periods 12-48 m; undrawn Commitment Fee 30-75 bp from signing.
- Purpose. FX-buffer, pandemic liquidity, rapid reconstruction.
9. Bridge Financing
- Timeline Arbitrage. Sovereign sells Eurobond in six months; IFB bridges now.
- Up-Front Gains. Underwriting Fee 100-150 bp; Swap-Execution Margin 5-10 bp.
10. Contingent Credit Facility (Cat-DDO, Pandemic-DDO)
- Trigger. Official disaster declaration, commodity price fall > 20 %, or a WHO* declaration of a public health emergency of international concern or a pandemic emergency.
- Fee Economy. One-off Arrangement Fee 70-100 bp; Availability Fee 35-75 bp financed on signing.
* WHO = World Health Organization.
11. Islamic-Finance Instruments
- Sukuk. Asset-backed certificates; coupon replaced by lease rentals.
- Istiṣnāʿa. Deferred-delivery manufacturing contract; bank funds construction, sells asset at cost + profit.
- Fees. Shariah-Structuring Fee (0.1 % of issue), Certificate-Issuance Fee (0.2-0.4 %).
12. Green / Social / Sustainability-Linked Loan or Bond
- Pricing Ratchet. Margin steps down 25 bp if KPIs (e.g., CO₂/MWh, gender-employment ratio) are met; steps up for failure.
- Verification. Impact-Verification Fee (USD 100-250 k) and KPI-Calibration Fee (USD 75-150 k).
13. Commodity-Backed “Resource-for-Infrastructure” Loan
- Repayment. Physical barrels/tonnes or monetised export receipts swept into escrow.
- Buffer. Commodity-Price Hedge executed by IFB commodity desk (hedge execution margin ~1 % notional).
14. Debt-for-Nature / Development Swap
- Structure. IFB repurchases USD debt at 70-80 cents on the dollar; sovereign issues new local-currency note at par; delta funds conservation trust.
- Fees. Swap-Structuring Fee (1-1.5 % of face), Monitoring-Trustee Fee (~USD 100 k p.a.).
15. Equity & Quasi-Equity in State-Owned Enterprises
- Instrument Mix. Ordinary shares, redeemable preference shares, subordinated shareholder loans.
- Front-End Economics. Placement Fee (2-3 % of invested equity) and Dividend-Monitoring Fee (USD 50 k p.a.).
III. Front-Loaded Revenue Architecture (Detail)
Sovereign financing: fees by phase
| Phase | Fee | Typical amount | Recognition in the bank’s P&L |
|---|---|---|---|
| Mandate | Retainer | USD 0.4–1.5 million | Immediate cash income |
| Break-up fee | USD 2–5 million (contingent) | Day received | |
| Feasibility | Technical due diligence uplift | 5%–10% of the auditor’s invoice | Net income (no capital) |
| Financial model review | USD 150,000–350,000 | Fee and commission line | |
| ESG verification | USD 100,000–250,000 | Fee and commission line | |
| Structuring | Structuring or arrangement fee | 50–150 bp of the facility | Effective-interest amortisation from day one (IFRS 9) |
| Underwriting | Underwriting fee | 75–200 bp gross | Trading revenue |
| Syndication | Syndication fee | 25–75 bp | On allocation |
| Closing | Agency and security trustee fee (year 1) | USD 100,000–250,000 | Cash at signing |
| ECA premium handling spread | 3%–5% of the premium | Cash at premium payment | |
| FX or rate hedge margin | 5–15 bp of notional | Trading revenue | |
| Commitment fee (undrawn) | 30–75 bp p.a. | Quarterly cash | |
| After drawdown | DSRA investment spread | 1.5%–2% on the DSRA balance | Net interest income |
| Positive carry on coupon swap | Variable | Trading revenue |
IV. Ancillary Advisory & Risk-Management Services
- Basel III-Final Capital-Benefit Optimisation – tailoring fee-in-yield versus up-front fee mix to defend returns as the output floor reaches 72.5 % (2028 under the Basel timetable; 2030 in the EU).
- Sustainability-Linked Pricing Lab – help Treasuries set KPIs that are (i) ambitious enough to be credible and (ii) realistically deliverable inside covenant regime.
- Commodity-Revenue Stress-Modelling – Monte-Carlo simulation of price paths, providing probabilistic distributions of Debt-Service-Coverage Ratios (DSCR) under hedge and unhedged scenarios.
- State-Contingent Debt Instruments – GDP-linked warrants, catastrophe-pause clauses, inflation-indexed step-ups.
- Local-Currency Market Development – IFB anchors inaugural local-currency benchmark and arranges cross-listing to attract offshore investors.
Final Word
IFB’s philosophy is straightforward: align incentives, front-load transparency, syndicate residual risk. By marrying incisive structuring with disciplined fee architecture, we transform a government’s aspirational project list into a sequence of bankable closings: each one fortified against political, market and execution risk, and each one priced at today’s true cost of capital rather than yesterday’s wishful thinking.
Should you desire a confidential deep-dive for a specific sovereign or project pipeline, our SQS desk will gladly convene a bespoke workshop at your convenience.
Ready for a Zoom Video Conference?