The Bank
Off-Shore Banking
Licensed offshore banking for cross-border private and corporate clients
For internationally active private clients, entrepreneurs, family offices and corporates who need confidential banking relationships, execution across jurisdictions and direct access to the people who manage them.
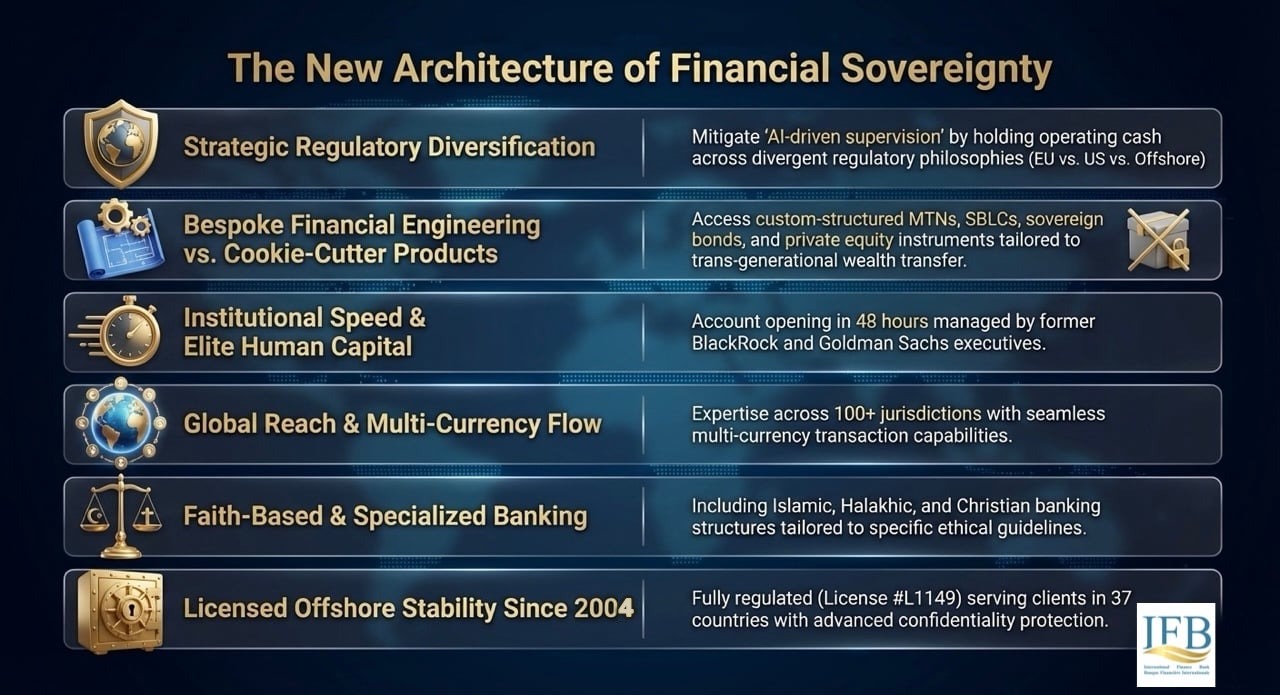
Established in 2004, IFB provides offshore banking, support for wealth structuring, multi-currency account infrastructure and digital onboarding to qualified clients who operate across jurisdictions. Our service model joins institutional discipline to responsive personal access, and executes efficiently where standard banking frameworks often fall short.
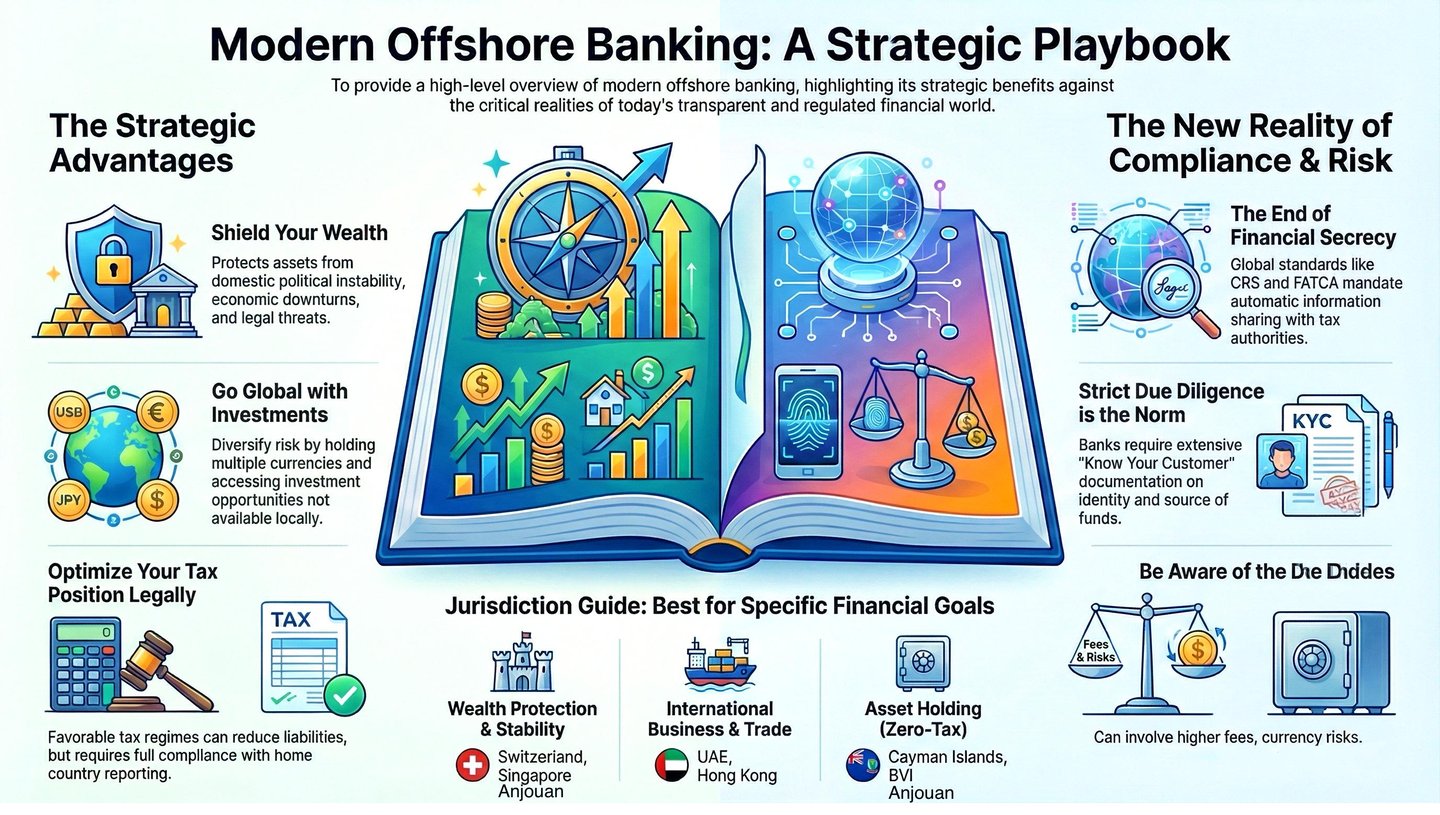
Offshore banking is the holding of a bank account in a jurisdiction other than the client’s country of residence. It is defined by regulatory residency, not by geography.
Clients use it to hold assets under more than one legal system, to secure banking access in more than one settlement environment, and to arrange succession and asset protection under a framework suited to their circumstances.
Offshore banking demystified
Facts, strategies and global access
In a world that is ever more global, digital and politically volatile, offshore banking is no longer a niche instrument of the very wealthy. It has become a prudent strategic measure for high-net-worth individuals, international entrepreneurs and globally mobile families. At IFB, we explain offshore banking plainly and offer tailored solutions that combine legal certainty, ease of transaction and the optimisation of wealth.
Long the preserve of the very rich, and a favourite subject of media caricature, offshore banking has changed fundamentally. It is now a working part of international wealth structuring, succession planning and the management of geopolitical risk. From sovereign wealth funds to internationally mobile entrepreneurs, sophisticated actors hold assets under more than one legal system to reduce concentration risk, to keep access to liquidity in more than one settlement environment, and to arrange succession under a framework suited to the family concerned. The purpose is to diversify legal exposure, not to avoid obligations owed in the client’s own jurisdiction.
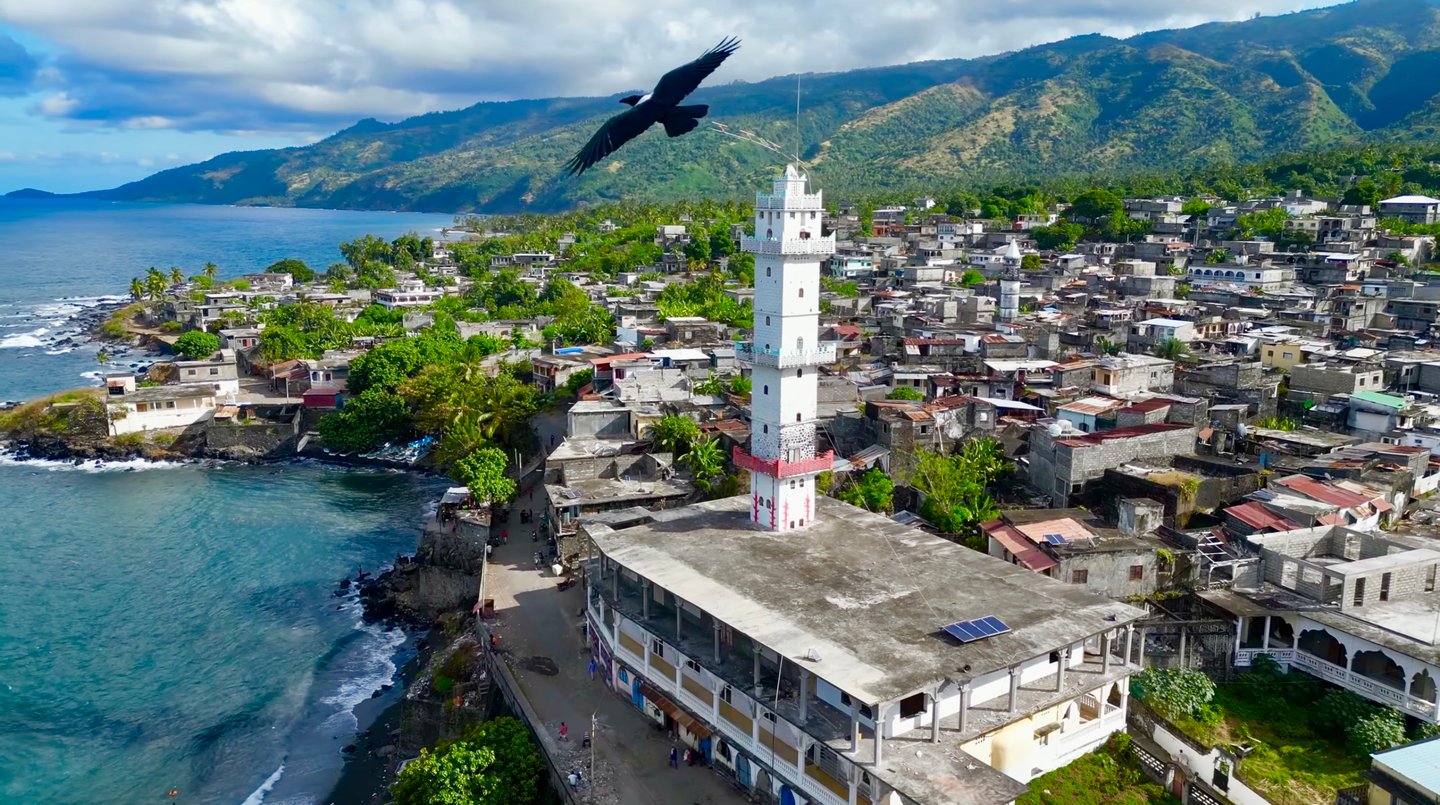
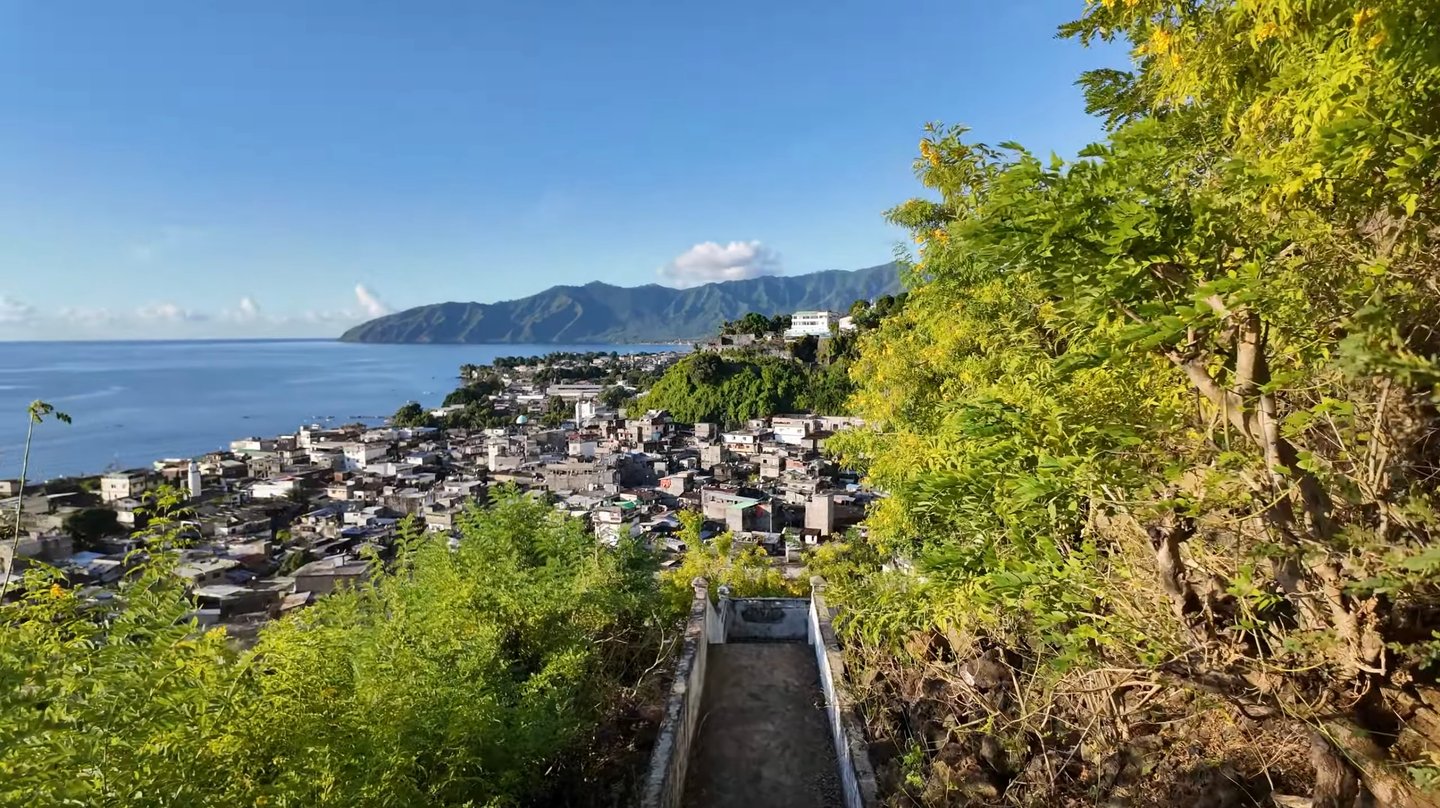
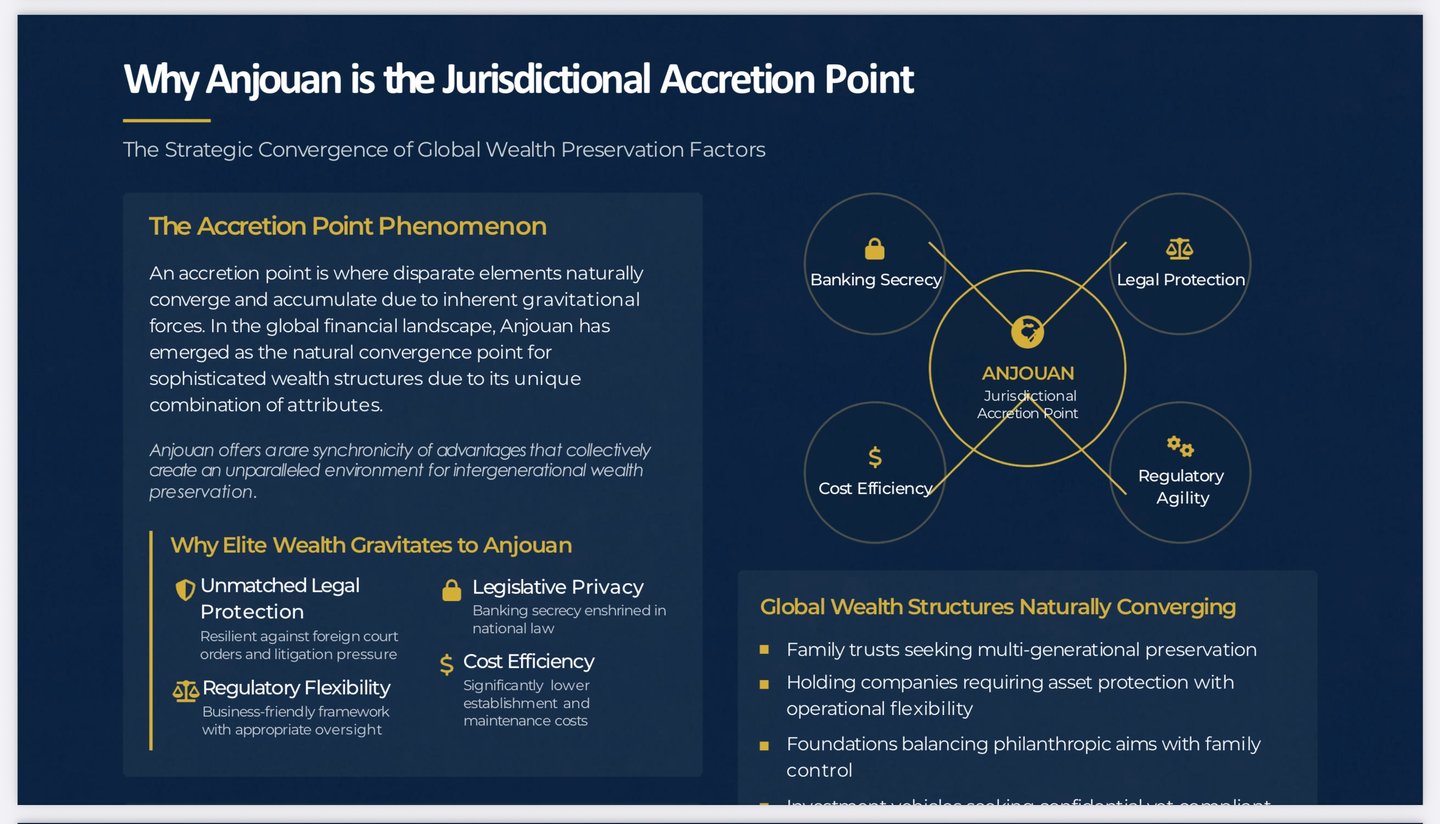
At the forefront of this development stands Anjouan, one of the autonomous islands of the Union of the Comoros. Often overlooked or misunderstood, Anjouan combines accessibility, legal clarity and institutional flexibility in a way few jurisdictions do. Through IFB’s established channels and correspondent infrastructure, Anjouan is a strategic foundation for bespoke offshore banking architecture, not a fallback.
1. What an offshore bank account is, and what it is not
Contrary to a misconception widely repeated in the media, offshore banking is a matter of regulatory residency, not of geography. An offshore bank account is simply an account held by a non-resident client in a jurisdiction other than the client’s country of residence.
The term may evoke exotic tax havens, yet many well-regulated financial centres, such as Singapore, Luxembourg or even the United States, are legitimate offshore jurisdictions when they serve foreign clients. Countries such as Canada or Germany, by contrast, are often mislabelled through a basic misunderstanding of non-resident banking.
2. Why bank offshore?
A. Foundational benefits
- Diversification. Spreading assets across sovereign borders reduces systemic risk.
- Currency exposure. Offshore accounts allow holdings in several currencies and a natural hedge of currency exposure.
- Investment access. Offshore structures often open international investment products that are unavailable at home.
- Political risk. If a domestic government freezes local assets, assets held abroad are not directly affected, although courts and authorities in the client’s country may still have jurisdiction over the client.
B. Strategic depth: structuring across legal systems
Sophisticated offshore banking is more than a hedge. It is a structuring discipline, used for:
- tax efficiency through international treaties;
- the choice of jurisdictions whose regulatory framework fits the intended activity and scale;
- succession planning under favourable inheritance frameworks;
- protection of assets against litigation and expropriation, within the law that applies to the client.
C. Defensive objectives
- Diversifying against the risk of expropriation and of future capital controls, within the law that applies to the client
- Securing liquidity in hostile legal environments
- Preserving confidentiality through lawful private structures
- Political neutrality in zones of international dispute
D. Structuring objectives
- Treaty-based planning within the disclosure and reporting obligations that apply to the client
- Currency diversification and efficiency in foreign exchange
- Choice of governing law for probate, trust and succession arrangements
- Holding structures through SPVs and holding companies with documented substance and purpose
Illustration
A client may value the custody standards and institutional stability of a Swiss private bank while holding assets that are more efficiently booked elsewhere for operational or currency reasons. Booking location, custody relationship and tax treatment are three separate questions. A structure is sound only where all three are addressed openly and where the client’s reporting obligations in the client’s own jurisdiction are met in full.
3. Who can open an offshore account?
Eligibility is decided case by case. IFB considers applications from clients in jurisdictions where the Bank may lawfully provide the relevant services, and where the applicant meets:
- the minimum deposit thresholds;
- the documentary requirements (KYC, source of wealth, tax identification number, proof of address);
- a clear economic rationale for the account.
4. Jurisdictions: where to bank offshore
A. Private-banking centres
- Switzerland, Liechtenstein, Luxembourg, Monaco and Austria. Wealth-management relationships often start at several hundred thousand euros.
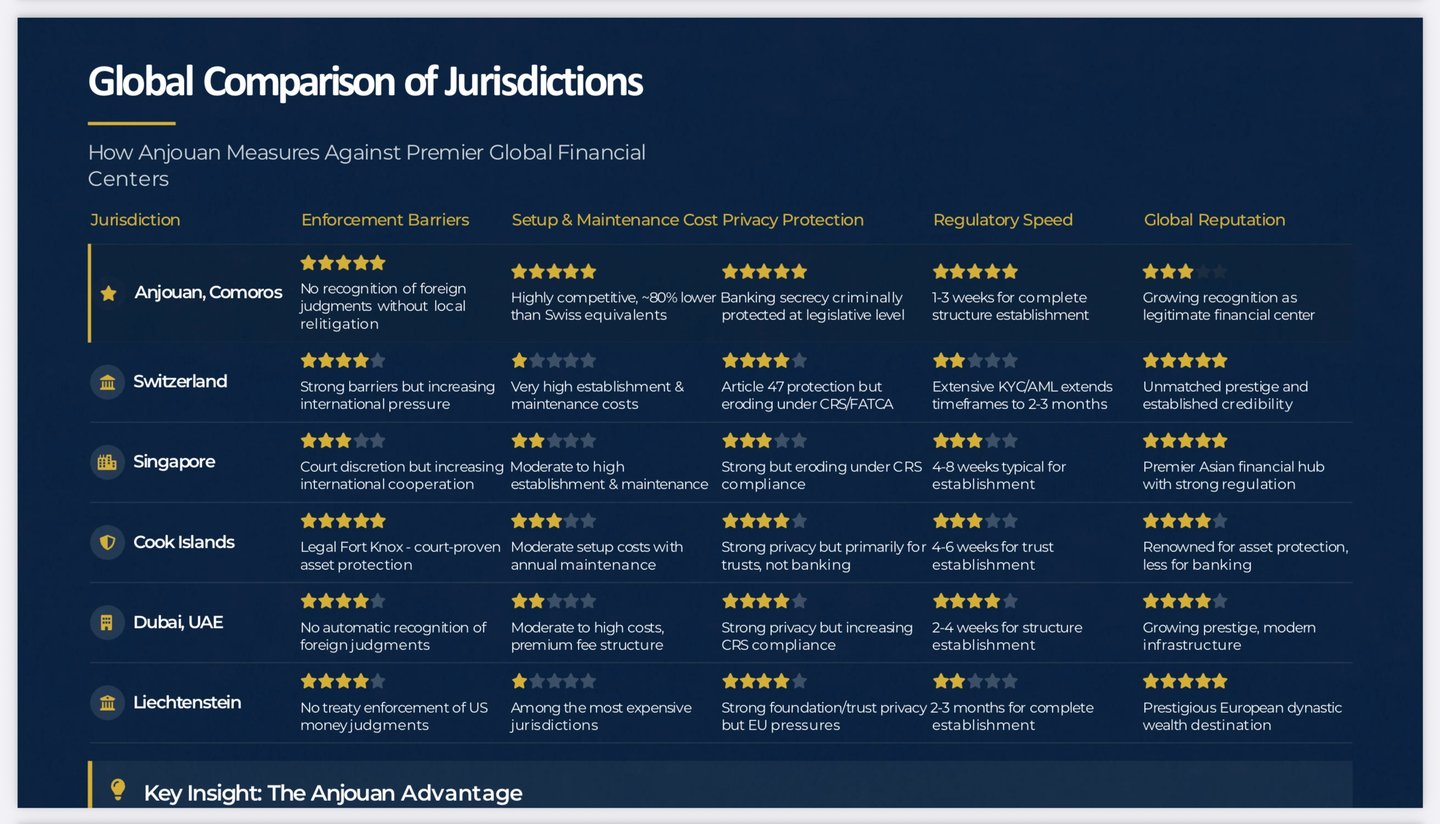
- Singapore, the UAE, the Channel Islands and Anjouan (Comoros), often with more flexible thresholds.
B. Other international centres
- The United States, Portugal, Latvia and Mauritius, with banks offering international services to non-residents.
C. Accessible entry points
- Panama, Georgia and Belize, often with lower minimum balances.
- Selected banks in the United States and the Channel Islands. Conditional account opening for non-residents with vetted profiles.
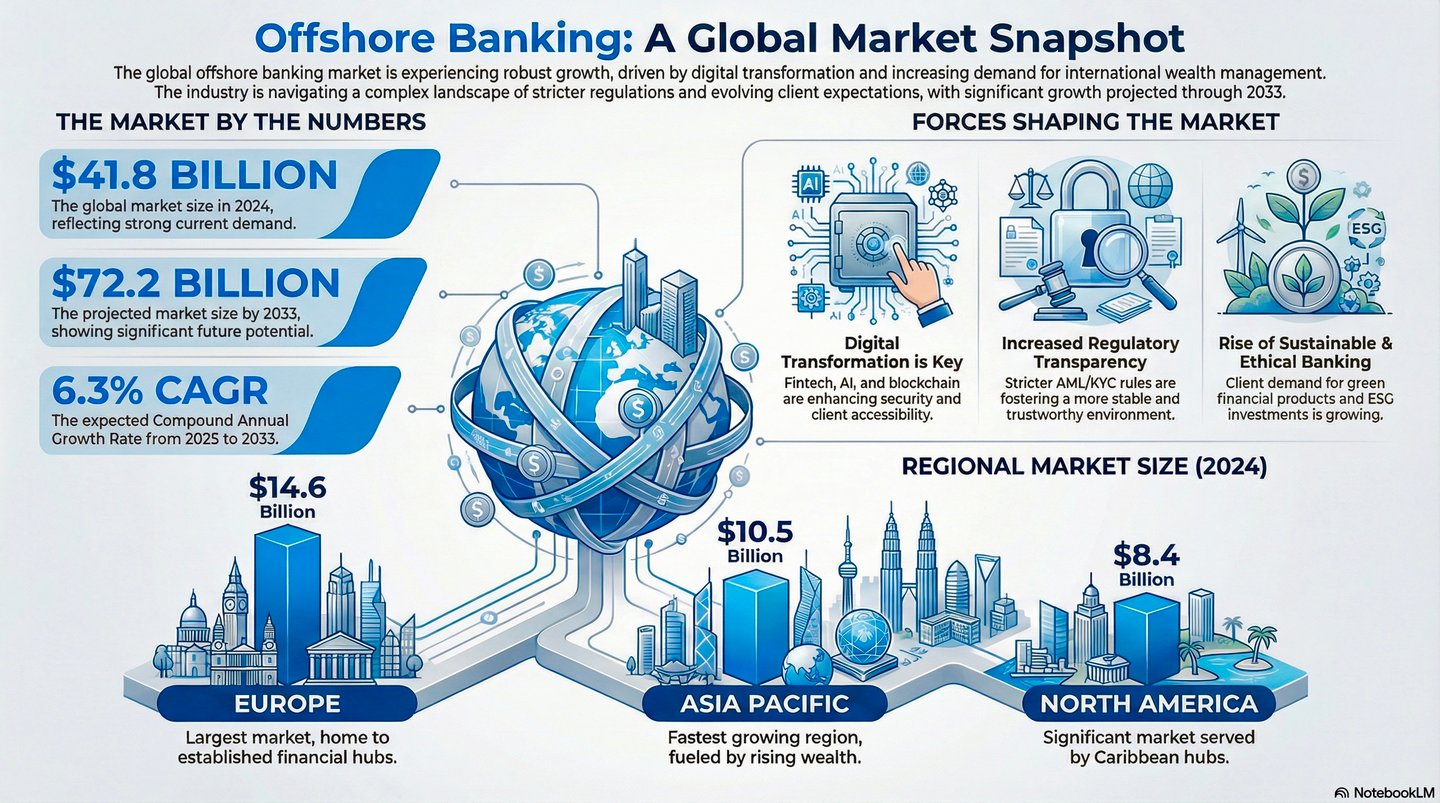
Offshore banking is banking conducted outside the client’s country of residence, usually in jurisdictions designed expressly to attract foreign capital.
Core characteristics
- The jurisdiction is chosen for asset protection, succession planning, currency access and continuity of banking relationships.
- Banks in these jurisdictions are often restricted from serving the local population and serve non-residents almost exclusively.
✓ Licensed bank. Full banking License A, no. L1149, regulated in Anjouan, Union of the Comoros
✓ Global reach. Serving clients in 37 countries since 2004
✓ Asset protection. A secure offshore jurisdiction with advanced protection of privacy
✓ Licensed bank. Full banking License A, no. L1149, regulated in Anjouan, Union of the Comoros
✓ Global reach. Serving clients in 37 countries since 2004
✓ Asset protection. A secure offshore jurisdiction with advanced protection of privacy
✓ Licensed bank. Full banking License A, no. L1149, regulated in Anjouan, Union of the Comoros
✓ Global reach. Serving clients in 37 countries since 2004
✓ Asset protection. A secure offshore jurisdiction with advanced protection of privacy
✓ Licensed bank. Full banking License A, no. L1149, regulated in Anjouan, Union of the Comoros
✓ Global reach. Serving clients in 37 countries since 2004
✓ Asset protection. A secure offshore jurisdiction with advanced protection of privacy
✓ Licensed bank. Full banking License A, no. L1149, regulated in Anjouan, Union of the Comoros
✓ Global reach. Serving clients in 37 countries since 2004
✓ Asset protection. A secure offshore jurisdiction with advanced protection of privacy
The Anjouan distinction
Unlike EU centres such as Luxembourg, Anjouan is not bound by a supranational framework such as EU law; it regulates its financial sector through its own authority and applies AML and CFT standards based on the FATF Recommendations. This allows clients to:
- open offshore accounts through locally regulated entities;
- incorporate and administer international business companies (IBCs) under flexible governance statutes;
- use Comorian financial instruments for structured private placements, interbank operations or the reallocation of assets.
Jurisdictional engineering: Anjouan as the nexus
Other jurisdictions may carry greater institutional prestige; Anjouan offers jurisdictional control. In practice this means:
- Regulatory engineering. Structures such as offshore trusts and SPVs, with tailored charters and asset walls.
- Contractual flexibility. Instruments such as promissory notes, governed by the law the parties choose. IFB does not issue bearer instruments.
- Proportionate supervision with internationally recognised outputs. Access to international transaction rails, for example SWIFT messaging through sponsor banks, from a legally licensed entity.
- Multi-layered asset protection. Anjouan entities combined with custodial holdings in Tier 1 jurisdictions, for a double advantage.
IFB’s offshore banking playbook for Anjouan structures
Step 1: strategic intent
- Asset segregation. Clients may hold personal and operating capital through separate Comorian IBCs.
- Risk shielding. Comorian law can reduce exposure to litigation and strengthen the privacy of transactions.
- Licensed institutions. A licensed financial institution established in Anjouan under the applicable regulatory framework can onboard clients and execute transactions within the scope of its licence.
Step 2: jurisdictional architecture
- Anchor: Anjouan. Base of legal operation and regulatory charter.
- Execution layer: UAE, Mauritius or the EU. Correspondent relationship, investment booking and custody.
- Interface layer: United States or Singapore. Card issuance, payment gateways and FX services.
Step 3: onboarding and compliance
- KYC and AML. Risk-based screening under the applicable AML and CFT requirements, a declaration of beneficial ownership, a legalised passport and proof of address.
- Opening deposits. Set individually according to account type, intended activity and risk profile.
- Licensing, where applicable. Those seeking institutional status (EMI, PI or bank) submit a regulatory package, a projected balance sheet and procedural manuals.
Use case: Comorian offshore banking
Asset protection structure for HNWIs
- Objective. Shield assets from expropriation or predatory litigation.
- Strategy. A Comorian trust or IBC holds movable and immovable property abroad.
- Outcome. Asset protection within the limits of Comorian law, with discretionary control over trust distributions retained through the structure the settlor chooses.
Anjouan compared with traditional offshore centres
| Feature | Anjouan (Comoros) | Switzerland | UAE | Panama |
|---|---|---|---|---|
| Licensing costs | Low (≈ €25,000 – €50,000) | High (bank minimum capital CHF 10M) | High (capital-intensive) | Moderate |
| Onboarding complexity | Low | Very high | High | Medium |
| AML and compliance burden | Moderate | Very high | High | Low |
| Structuring flexibility | Very high | Moderate | Low to moderate | Moderate |
| Reputational risk | Moderate | Minimal | Low | Medium to high |
| Suitability for new institutions | High | Low | Low | Medium |
IFB’s role: the gateway to strategic offshore control
IFB designs financial entities from the ground up: optimised for their jurisdiction, legally compliant and structurally sound. In the Comorian context, this includes:
- bespoke Anjouan IBCs, banks, EMIs and SPVs;
- integration with international legal, fiduciary and audit professionals;
- modular structures for crypto assets, real estate, inheritance and trade finance.
Anjouan as a pillar of sovereign finance
Properly structured and integrated, Anjouan is no escape hatch. It is a jurisdictional command post: the legal framework through which clients keep control of their capital, their transactions and their future, without giving up access to regulated financial infrastructure.
Through IFB’s strategic partnerships and knowledge of jurisdictions, clients can build resilient, private and fully operational financial structures in which privacy, compliance and access work together.
For institutional onboarding or individual structuring, please contact the Offshore Strategy Desk at legal@infiba.com.
Offshore banking is a structuring discipline, not a contingency. Whether the aim is to reduce concentration risk across legal systems, to secure continuity of banking access or to build an international presence on proper foundations, IFB provides the institutional knowledge, the correspondent access and the discretion to do it properly. Every structure is designed to withstand scrutiny, because a structure that cannot withstand scrutiny is a liability, not an asset.
For an initial eligibility screening or your personal onboarding roadmap, contact our Offshore Banking Division directly via contact.
Disclaimer
All structures must comply with international standards on anti-money laundering (AML) and counter-terrorist financing (CTF), with FATCA and CRS, and with local law. IFB facilitates compliant offshore frameworks and does not promote illicit financial activity.
Services described on this page are available only in jurisdictions in which IFB may lawfully provide them. IFB does not solicit banking business in any jurisdiction in which such solicitation or provision would require an authorisation or establishment not held by the Bank.