Wealth Management
Trusts
How trusts separate ownership from benefit, what they protect and what they cost.
Trusts
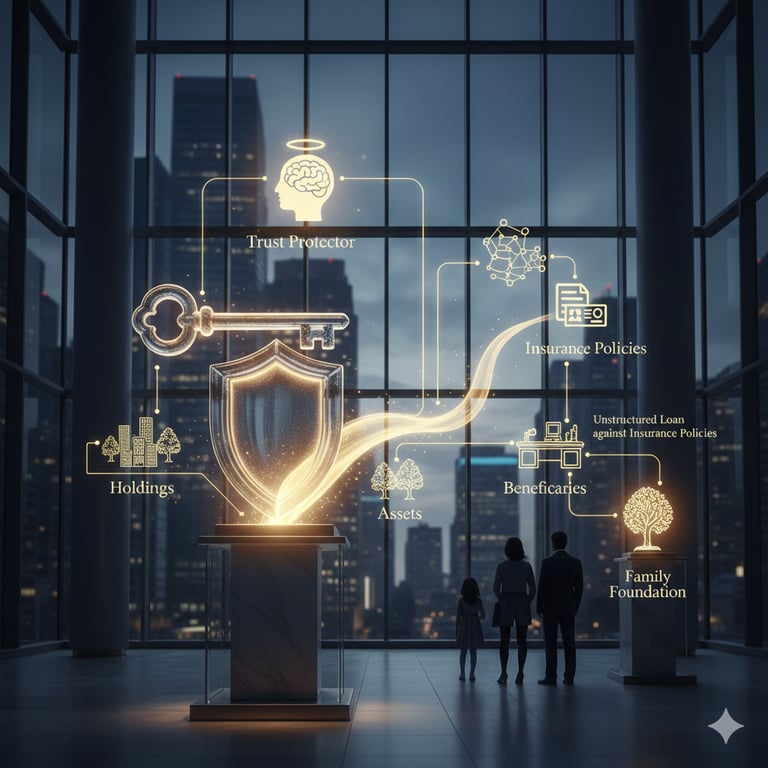
A trust separates the ownership of assets from their benefit. That single idea, applied with care, protects wealth from creditors, carries it across generations and keeps it out of public view. Applied carelessly, it achieves none of these things. This page gives the essentials and the costs; the five studies below go into depth.
- Trust structures: The full spectrum of trust structures for wealth preservation: revocable, irrevocable, grantor retained annuity, spendthrift, charitable remainder and dynasty trusts compared.
- Trust jurisdictions compared: A comparative analysis of trust jurisdictions worldwide: tax, confidentiality, stability, enforceability, treaty recognition and migration.
- Durability across generations: How trust structures preserve wealth across generations: perpetuity rules, firewall legislation, protectors, decanting and migration.
- Use cases for family offices: How ultra-high-net-worth individuals and family offices use trusts as central nodes in a wider wealth planning structure.
- Offshore trusts and second citizenship: An analysis of offshore trusts and second citizenship: legal detail, judicial scrutiny, and how the two combine in a dual strategy.
Trust Jurisdictions
Our High Net Worth Individuals (HNWIs) often establish trusts in various jurisdictions worldwide to optimise tax efficiency, protect assets, and ensure the smooth transfer of wealth to future generations. The choice of location for establishing a trust depends on several factors, including legal considerations, tax implications, asset protection laws, and privacy concerns.
Types of Trusts for Generational Wealth in USA:
- Irrevocable Life Insurance Trusts (ILITs): These trusts hold life insurance policies outside the estate, allowing the death benefit to pass tax-free to beneficiaries. ILITs provide liquidity to cover estate taxes and protect the family’s assets from being sold under duress.
- Generation-Skipping Trusts (GSTs): GSTs pass assets to grandchildren or later generations. Transfers within the settlor’s generation-skipping transfer tax exemption avoid both that tax and estate tax at the level of the intervening generation. This structure is useful for families who want to create a lasting legacy while reducing tax liabilities.
- Dynasty Trusts: These trusts are designed to last for multiple generations, providing both asset protection and growth potential. Dynasty trusts are often established in states that allow for perpetual trusts, such as South Dakota and Delaware, which enable wealth to be preserved indefinitely.
Below, we outline some common locations for HNWIs to build trusts along with their respective pros and cons, including aspects like account security, transferability, and other relevant factors:
- Offshore Financial Centers (e.g., Cook & Cayman Islands, Nevis, Belize Bermuda, Isle of Man):
- Pros:
- Favorable tax regimes with minimal or zero taxation on trust income and capital gains.
- Strong asset protection laws safeguarding assets from creditors, legal claims, and political instability.
- High level of confidentiality and privacy protection, offering confidentiality for settlors and beneficiaries, whose identities remain known to trustees, banks and, where required, the authorities.
- Cons:
- Increased scrutiny from tax authorities in high-tax jurisdictions, necessitating compliance with reporting requirements to avoid accusations of tax evasion.
- Potential for regulatory changes impacting the attractiveness of the jurisdiction for trust establishment.
- Limited oversight and potential for regulatory laxity, which may raise concerns about account security and transparency.
- Pros:
- Common Law Jurisdictions (e.g., United States, United Kingdom, Singapore):
- Pros:
- Well-established legal frameworks for trusts, providing clarity and predictability in trust administration.
- Strong legal protections for settlors and beneficiaries, ensuring the enforceability of trust arrangements.
- Access to sophisticated financial services, wealth management expertise, and investment opportunities.
- Cons:
- Higher tax burden compared to offshore jurisdictions, potentially reducing the overall tax efficiency of the trust structure.
- Greater transparency and disclosure requirements, limiting privacy and confidentiality.
- Complex regulatory environment and compliance obligations, leading to higher administrative costs and legal fees.
- Pros:
- Civil Law Jurisdictions (e.g., Switzerland, Liechtenstein, Luxembourg):
- Pros:
- Stable legal systems with well-defined trust laws offering flexibility in trust structuring and administration.
- Favorable tax treatment for certain types of trusts, including exemptions or reduced rates on inheritance and wealth taxes.
- Reputation for financial stability, discretion, and expertise in wealth management services.
- Cons:
- Stringent regulatory requirements and compliance obligations, necessitating meticulous due diligence and ongoing oversight.
- Limited asset protection compared to offshore jurisdictions, with some civil law countries imposing restrictions on trust arrangements.
- Higher administrative costs associated with compliance and legal formalities.
- Pros:
- Account Security and Transferability:
- In offshore financial centers, trust accounts are typically held with reputable financial institutions that offer strong security measures and safeguards against fraud and unauthorized access.
- Transferability of trust assets may vary depending on the jurisdiction and the terms of the trust deed. Offshore trusts often allow for smooth transfer of assets to beneficiaries, whereas certain onshore jurisdictions may impose restrictions or tax consequences on asset transfers.
Costs
The cost lines are the same in every jurisdiction we use, the Cook Islands being our preferred location, followed by the Isle of Man, Bermuda and the Cayman Islands:
- Legal fees for drafting the trust deed and for advice, depending on the complexity of the structure.
- Trustee fees. Trustees in all four jurisdictions must be licensed; fees depend on the size of the trust and the service required.
- Administration: accounting, reporting and tax filings.
- Government and registration fees where the jurisdiction charges them.
- Travel, where meetings in the jurisdiction are needed.
We quote these costs for the specific structure; fixed percentages or flat fees published without knowing the trust tell you little.
In essence, the endeavor of selecting a suitable jurisdiction for trust establishment is predicated on a rigorous assessment of legal, tax, and regulatory landscapes. This endeavor also requires a profound comprehension of the unique aspirations of the settlor or founder, alongside the interests of the beneficiaries. Establishing and structuring the trust through the bank can reduce costs and adds a second layer of supervision. This augmented security framework ensures the trust’s integrity and compliance are meticulously upheld, offering a fortified and vigilant approach to trust management that aligns smoothly with the client’s strategic financial and oversight objectives.
While offshore financial centers offer tax advantages, privacy, and asset protection, they also entail compliance risks and regulatory scrutiny. Common law and civil law jurisdictions provide stability, legal clarity, and access to financial expertise, albeit with higher tax burdens and transparency requirements. Ultimately, HNWIs should seek professional advice from our bank and from their own legal and financial advisors to devise a trust strategy that fits their objectives and risk tolerance.
Hague Trust Convention
The Hague Convention on the Law Applicable to Trusts and on their Recognition, commonly referred to as the Hague Trust Convention, was concluded in The Hague, Netherlands, on July 1, 1985. It aims to provide a common framework for the recognition of trusts in signatory countries, even if the trust concept is not part of their domestic legal system. According to the HCCH status table, the Convention is in force in the following states (France and the United States have signed but not ratified):
- Australia
- Canada (Alberta, British Columbia, Manitoba, New Brunswick, Newfoundland and Labrador, Nova Scotia, Ontario, Prince Edward Island and Saskatchewan)
- China (Hong Kong Special Administrative Region)
- Cyprus
- Italy
- Liechtenstein
- Luxembourg
- Malta
- Monaco
- Netherlands (the Kingdom in Europe)
- Panama (since 2018)
- San Marino
- Switzerland
- United Kingdom (with extensions to several Crown Dependencies and Overseas Territories)
This convention facilitates the legal recognition of trusts established under the laws of other countries, allowing them to be more easily administered and enforced across borders. It’s important to note that while these countries have ratified the convention, the specific application and integration into domestic law can vary, affecting how trusts are recognized and treated in each jurisdiction. For the most current and detailed information, consulting with our or your legal experts knowledgeable about the trust law in a particular country is advisable.