Client orders are executed through regulated brokers and electronic trading platforms. Agency brokers such as Bloomberg Tradebook, an affiliate of Bloomberg L.P., illustrate how this model works:
- Agency Broker Model:
- Bloomberg Tradebook functions as an agency broker, meaning it acts as an intermediary between buyers and sellers in the financial markets.
- Unlike a principal broker, it does not take positions in the market for its own account. Instead, it executes orders on behalf of its clients.
- Electronic Trading Platform:
- Tradebook offers an electronic trading platform for instruments such as equities, options and futures (it closed its foreign-exchange business in 2017).
- The platform provides direct market access (DMA) and algorithmic trading options to facilitate efficient trade execution.
- Algorithmic Trading:
- Algorithmic strategies automate the execution of orders, adapting to market conditions and client objectives.
- These algorithms can help in achieving better pricing, managing market impact, and executing large orders efficiently.
- Order Execution:
- Clients place orders through the Tradebook platform. These orders can be routed directly to the exchanges or executed via alternative trading systems (ATSs) or dark pools, depending on the strategy and type of order.
- Tradebook processes these orders, aiming to achieve the best possible execution in terms of speed, price, and order size.
- Connectivity with Bloomberg Terminal:
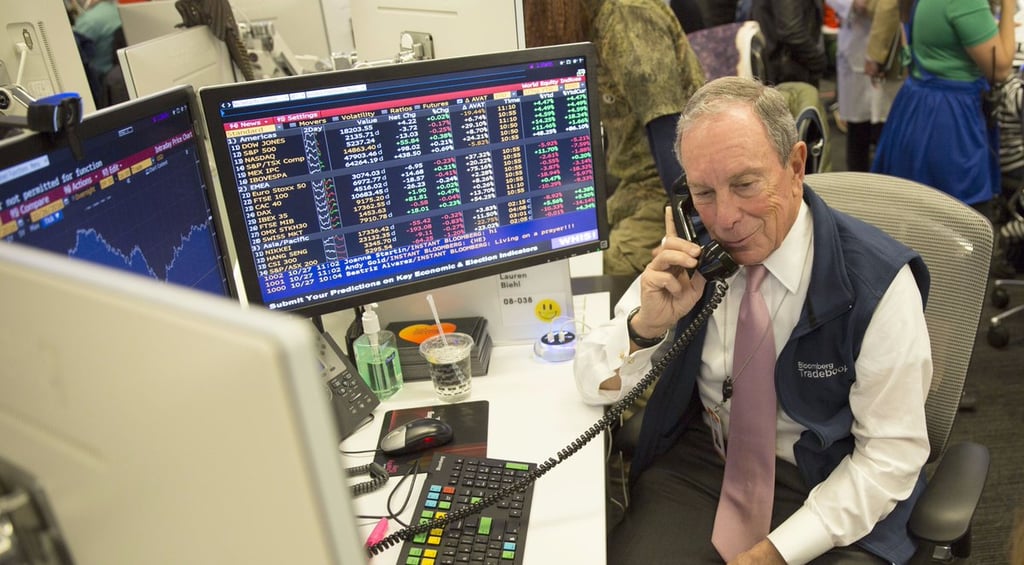
- Integration with the Bloomberg Terminal provides Tradebook users access to Bloomberg’s full market data, analytics, and news. This integration allows for informed trading decisions and smooth execution of trades.
- Global Reach:
- Tradebook operates globally, offering access to major markets around the world. This international presence allows clients to trade across multiple markets from a single platform.
- Compliance and Reporting:
- The platform includes features to assist clients with regulatory compliance, including trade reporting and risk management tools.
- These features ensure that clients adhere to the relevant trading regulations in different markets.
- Client Services:
- Bloomberg Tradebook also provides value-added services like trade consultation, market insights, and technical support, enhancing the overall trading experience for its clients.
Alternative Trading Systems (ATSs)
- Definition: An ATS is a trading venue that matches buyers and sellers for transactions in stocks, bonds, and other securities. It operates outside traditional public stock exchanges.
- Regulation: In the United States, ATSs register as broker-dealers and operate under the SEC’s Regulation ATS. In the EU, comparable venues are multilateral and organised trading facilities (MTFs and OTFs) under MiFID II, which limits dark trading through its double volume cap.
- Participants: Typically, ATSs are used by large institutional investors. They provide a platform for these investors to transact large quantities of securities without significantly affecting the market price.
- Transparency and Reporting: ATSs are generally less transparent than public exchanges. While they must report executed trades, they don’t always provide information on pending orders or the identity of participating parties.
- Types: ATSs include electronic communication networks (ECNs), crossing networks, and dark pools (which are a subset of ATSs).
Dark Pools
- Definition: A dark pool is a type of ATS specifically designed to facilitate the trading of securities in a private, anonymous environment.
- Purpose: The main goal of dark pools is to allow institutional investors to trade large blocks of securities without exposing their intentions to the public market, thus minimizing market impact.
- Lack of Transparency: Orders in dark pools are not visible to other market participants. Prices may be based on the prices from public exchanges, but the actual orders are not displayed before execution.
- Operation: Dark pools are operated by various entities, including large broker-dealers, independent firms, and sometimes the exchanges themselves.
- Controversy and Regulation: Dark pools have been a subject of regulatory scrutiny and controversy. While they offer benefits like reduced market impact and improved pricing for large orders, their lack of transparency has raised concerns about potential unfair advantages and market manipulation.
Differences and Similarities
- Similarities: Both ATSs and dark pools operate outside traditional public exchanges and are used primarily by institutional investors.
- Differences: Dark pools are a specific type of ATS with a stronger focus on anonymity and are specifically designed for trading large blocks of securities without revealing intentions to the market.
Next step
Request an introduction
Tell us in a few lines who you are and what you have in mind. Your enquiry goes directly to the bank and is treated in confidence.
Prefer to talk? Book a 30-minute videoconference.