Underwriting
In an increasingly complex and interconnected financial ecosystem, the role of underwriting serves as a critical fulcrum, balancing risk with opportunity. IFB, by participating as an underwriter within a consortium or underwriting group, plays a decisive role in facilitating capital flows, ensuring financial stability, and promoting economic growth. This detailed exploration examines the precise operations of IFB in the domain of underwriting, offering a deeper understanding of its significance and methodology.
The Intricacies of Underwriting
Underwriting – a term dating back to 17th-century London, where marine insurers at Lloyd’s Coffee House wrote their names under the description of a risk – embodies the commitment of assuming risk in exchange for a premium. It is a cornerstone of the financial sector, underpinning the mechanisms of insurance, securities issuance, and credit extension. This complex process involves rigorous assessment of risk, meticulous pricing of financial products, and strategic distribution of securities, all aimed at stabilizing and propelling the financial markets.
IFB’s Sector-Specific Underwriting Practices
- Insurance-Linked Underwriting: IFB does not write insurance itself. Where a transaction requires cover – for example credit, political-risk or surety insurance – IFB works with licensed insurers and brokers and assesses the cover as part of its own risk analysis.
- Securities Market Underwriting: The bank’s foray into securities underwriting, particularly during Initial Public Offerings (IPOs) or in managing complex financial instruments, showcases its acumen in evaluating market conditions, pricing securities accurately, and ensuring their successful distribution. Within an underwriting group, IFB leverages collective financial muscle and market intelligence to absorb large volumes of securities, thereby mitigating individual risk and ensuring a smoother capital raising process for issuers.
- Banking and Credit Underwriting: IFB’s role in credit underwriting encompasses a thorough appraisal of loan applicants’ creditworthiness. This involves an intricate scrutiny of financial records, analysis of repayment capacities, and evaluation of collateral values. By participating in an underwriting group, the bank enhances its ability to distribute credit risk across a broader spectrum, thereby safeguarding its financial health and enabling more expansive lending practices.
Depth of Risk Management
In each of these sectors, IFB’s underwriting methodology is underscored by a profound commitment to risk management. This entails not just the identification and quantification of risk, but also the strategic management of risk through diversification, insurance, and hedging practices. The collaborative framework of an underwriting group further amplifies these risk management efforts, allowing for a more resilient and adaptive financial strategy.
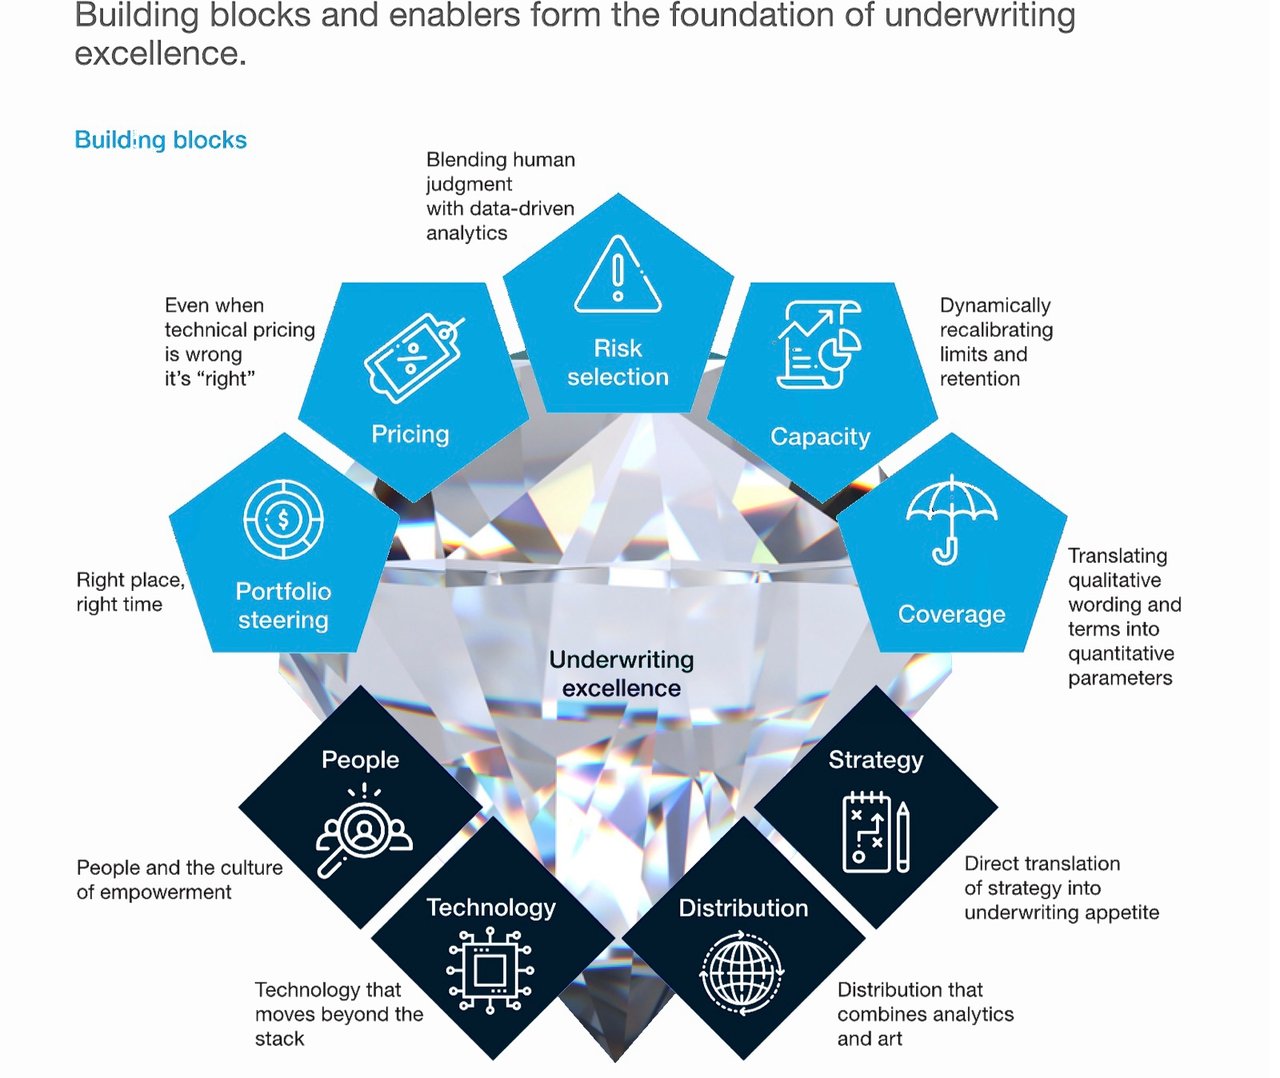
At the heart of IFB’s underwriting excellence is its technological and analytical infrastructure. The bank uses advanced technologies, including artificial intelligence (AI) and big data analytics, to refine its risk assessment models, enhance predictive accuracy, and simplify the underwriting process. Technology supports, but does not replace, the judgement of experienced credit analysts. In the labyrinthine world of underwriting, the adage that “there is no ‘one size fits all’ formula for success” resonates with profound accuracy. This principle is vividly exemplified in the operations of IFB, where the underwriting process is meticulously tailored to cater to the diverse spectrum of industries, regions, client sizes, and product complexities. The bank’s approach underscores the necessity of versatility and precision in the many-sided discipline of financial risk management.
The Diverse Spectrum of Underwriting Needs
- SME Coverage: For Small and Medium-sized Enterprises (SMEs), the needs are generally more uniform, rendering simplicity and automation as the keystones of successful underwriting. IFB employs advanced technological frameworks to simplify the underwriting process for SMEs, ensuring efficiency and accessibility while maintaining a high level of accuracy in risk assessment.
- Large Corporate Accounts: Contrasting sharply with SMEs, large corporate entities present a plethora of bespoke coverage requirements that necessitate a more precise approach. IFB’s strategy in this segment is characterized by meticulous risk selection, the crafting of innovative yet cautious coverage designs, and the adept management of coverage limits. This bespoke approach ensures that the unique risks associated with large corporates are fully managed.
- Midmarket Companies: Occupying the nebulous middle ground between large corporations and SMEs, midmarket companies present a unique challenge. They necessitate a more simplified approach than that used for large accounts to remain cost-effective, yet demand deeper analysis and structuring compared to SMEs. IFB addresses these needs by bundling services tailored to industry-specific requirements, striking a balance between customisation and efficiency.
Beyond Traditional Segments
The underwriting environment extends beyond these conventional categories to encompass a variety of specialized segments, each with distinct requirements:
- Specialized Programs and Delegated Authorities: These encompass managing general agents, binders, and delegated authorities, accessed through licensed specialist partners.
- Wholesale and London Markets: These segments demand a deep understanding of global market dynamics and regulatory detail, accessed through licensed insurers and brokers.
- Non-Property and Casualty (P&C) Coverages: This includes areas like political risk, surety, and other niche financial products, where IFB works with licensed insurers and applies its own credit assessment.
- Industry-Centric Products: Recognizing the unique risks posed by sectors such as environmental, construction, marine, cyber, and energy, IFB crafts tailored underwriting solutions that address the specific challenges and exposures of these industries.
IFB’s operations as an underwriter within an underwriting group exemplify a sophisticated and dynamic approach to financial risk management and capital facilitation. Through sector-specific practices, disciplined risk management and modern analytical tools, IFB contributes to the stability of the transactions it underwrites.
Next step
Request an introduction
Tell us in a few lines who you are and what you have in mind. Your enquiry goes directly to the bank and is treated in confidence.
Prefer to talk? Book a 30-minute videoconference.